Signal vs. Noise: Stock Market Concentration Concerns
The Player or the House?
We’re in the Hospitality Business
Client-Exclusive Webinar with David Booth, Co-Founder and Chairman of Dimensional
A Good Estate Plan Should Make Life Easier
Author: Matt Hall
Five Things I Was Wrong About
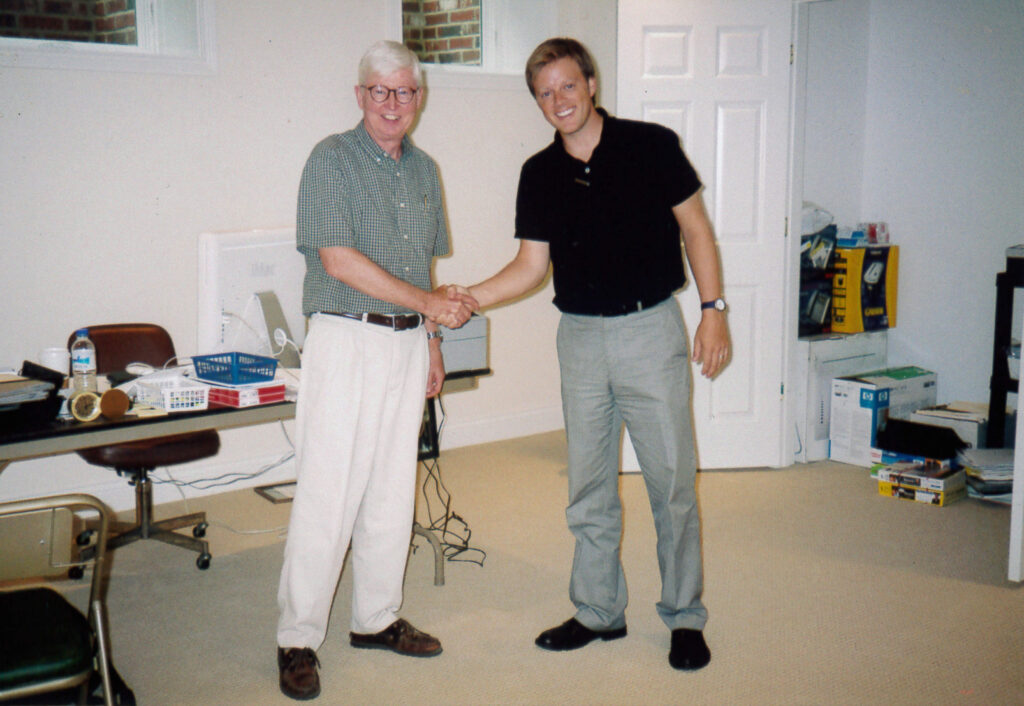
We started Hill Investment Group with some pretty strong convictions. Some have stood the test of time. Others? Not so much.
I’ve always believed in having the courage of your convictions. But I’ve also learned there’s a difference between conviction and certainty. One gives you the confidence to act. The other can prevent you from learning. Here are five things I got wrong along the way.
1. I thought the entire investment industry would eventually come around.
When we started HIG, I thought it was only a matter of time before everyone embraced evidence-based investing. The academic research was, and is, so compelling. The math made sense. Why wouldn’t all investors eventually get on board? To be fair, far more people invest this way today than they did 21 years ago. That’s real progress.
But I’m still amazed by what we see when prospective clients arrive from some of the biggest names on Wall Street. High fees. No coherent investment philosophy. Poor asset allocation and asset location. Sloppy execution. In many cases, it’s not much different from what we saw two decades ago.
I was naive to think the evidence alone would persuade everyone. What I underestimated was how people actually make decisions. Relationships, familiarity, incentives, emotions, and plain old inertia often carry more weight than the math. I’ve become more curious about why people believe what they believe, even when I strongly disagree with their conclusions. Understanding what motivates someone is often more useful than simply explaining why the data and evidence tell a different story.
2. I thought hiring great people would be easy.
This one is almost embarrassing to admit. In our early days, someone could practically get hired because they were available, enthusiastic, and told Rick and me how wonderful we were. We liked them. They liked us. What could go wrong? Plenty, as it turns out. How dumb was that?
We confused enthusiasm with ability and flattery with fit. We weren’t nearly disciplined enough about assessing skills, character, values, or whether someone would actually make the team better. Today, we’re much more intentional and mature. We look for what we call “caring nerds”. People who take ownership, solve problems, get satisfaction from serving others, and make those around them better. People who look for solutions instead of excuses.
And even with a better process, hiring is hard. Really hard. I’ve learned that one exceptional person can make an enormous difference, while one wrong person can consume an extraordinary amount of time and energy. Don’t hire people because they like you. Hire people because they make your team better.
3. I thought everyone needed to work in the same office.
I love having our team together. There’s an energy that comes from being in the same room, sharing ideas, laughing, and building relationships that you can’t completely replicate on a screen. But I used to think everyone needed to work in the same office. I was wrong.
I’d much rather have an extraordinary person in Nashville, Houston, or somewhere else than settle for someone less capable simply because they live in St. Louis. And think about how fortunate we are. Someone can get almost anywhere in the country in a day. We have incredible technology that allows us to collaborate across time zones. Why would we limit ourselves to hiring people who happen to live nearby?
That doesn’t mean being together is unimportant. Quite the opposite. It means we need to be deliberate about when and how we get together. The goal isn’t to build the best team within driving distance. It’s to build the best team, period.
4. I thought our reputation within the industry mattered enormously.
Early in my career, I cared a lot about what other financial advisors thought of us. I wanted our peers to respect what we were building. Today, I care a whole lot less.
That’s not because I don’t respect the profession. There are some terrific people doing outstanding work.
But after 21 years, I’ve also seen enough mediocre advice, questionable practices, and self-congratulation to know that industry approval isn’t much of a scorecard. Frankly, there are fewer than ten firms in the country I’d feel completely comfortable recommending to someone I care about. So why should I spend much time worrying about what the rest of the industry thinks?
What matters is what our clients think. Do they trust us? Are we improving their lives? Are we delivering on our promises? Would they enthusiastically recommend us to someone they love? Those are questions worth obsessing over. I’ve learned to spend less energy seeking approval from our peers and more energy earning the trust of the people who have chosen us.
5. I thought the best part of my job would be helping people build enormous wealth.
When Rick and I started HIG, I assumed the most rewarding part of the business would be helping people accumulate substantial wealth. And don’t get me wrong. Investment results matter. A lot. We’re serious about investing, and we should be. Our clients have entrusted us with something enormously important.
But what I didn’t anticipate was how satisfying it would be to see that financial security make a difference in someone’s life. Sometimes it’s something wonderful. A retirement, a family celebration, an opportunity to do something meaningful. Other times it’s something nobody would wish for. A serious illness. The loss of a spouse. An unexpected family crisis.
In those moments, money can’t solve everything. Not even close. But having a sound financial plan and the resources to support it can take an enormous burden off someone’s shoulders. Knowing we’ve played a part in creating that security is incredibly rewarding.
We still love helping people build wealth, but we’ve learned that the real satisfaction comes from seeing what that wealth allows them to do, enjoy, endure, or overcome. The money matters. What the money makes possible matters more.
After 21 years, I’m more convinced than ever about the investment philosophy that led Rick and me to start Hill Investment Group. But I’m also more aware of how much I don’t know. Building a business, leading people, and serving clients have taught me that curiosity and humility aren’t weaknesses. They’re strengths. I’m proud of what we’ve built, but even more interested in what we can become if we keep questioning our assumptions and learning.
That’s part of what it means to Take the Long View. Have the courage of your convictions, but never confuse conviction with certainty.
Matt
We’re in the Hospitality Business
If you’ve spent much time in St. Louis or eaten your way around New York, you probably know the name Danny Meyer. The St. Louis native is behind some of New York’s most celebrated restaurants and, of course, Shake Shack.
I’ve been following Danny’s work for a long time. Years ago, I had him on my podcast to talk about his approach to hospitality. He was back home in St. Louis recently, and we sent several Hill team members to hear him speak. This week, I’m leading our team book club on Unreasonable Hospitality: The Field Guide by Will Guidara, who worked with Danny before going on to lead Eleven Madison Park.
Why does an investment firm spend this much time studying people in the restaurant business? Because we’re in the hospitality business, too.
Danny has long made a distinction that has stuck with me: service is what you do. Hospitality is how you make people feel.
That idea isn’t new to Hill. When we founded the firm in 2005, we wanted to build something that felt different. Personal. Thoughtful. The kind of place where people knew your name, knew your family and cared about what was happening in your life.
At our best, we’ve done that for more than 20 years. But here’s something I’ve come to appreciate: culture isn’t enough if the experience depends on which person you happen to get.
For years, much of our hospitality came naturally from great people doing what great people do. As we’ve grown, we’ve realized we need to be more intentional. The standard can’t be that some people at Hill are exceptional at making clients feel known and cared for. It has to be the Hill standard.
So we’re working to turn something that has always been part of our culture into something more consistent and durable. We’re hiring for it. We’re teaching it. We’re talking about it. We’re rewarding it. And, importantly, we’re asking clients whether we’re actually delivering it.
This summer, we conducted our first comprehensive client survey. Nearly half of our client households participated, and the overall results were excellent. But two comments mattered more to me than any score.
One client told us Hill was the first financial advisor she’d ever had where she felt “truly seen and heard.”
Another told us, “I don’t have a sense that they know me know me.”
That’s hospitality in two sentences.
The first is what we’re trying to create. The second is a reminder that we don’t create it consistently enough yet.
Of course, none of this diminishes the importance of the actual advice. A great restaurant still needs great food.
For years, we’ve been obsessive about the investment side of the equation: evidence instead of prediction, reasonable costs, tax efficiency and thoughtful portfolios built around what someone is actually trying to accomplish. We still are.
But great investments are not the end goal. They’re in service of something bigger.
We want you to trust the plan enough that you don’t have to spend your life thinking about it. We want to understand what matters to you, anticipate what you might need and be there when life changes.
That’s the experience we’re trying to make more consistent.
Great hospitality shouldn’t depend on getting the right person on the right day. It should be something you can count on from Hill.
We’re not trying to become something different as we grow.
We’re trying to become more consistently who we’ve always wanted to be.
The Player or the House?
August has been a month of goodbyes for me.
Lisa and I just dropped off our only child at college. Like every parent who has reached this milestone, I’m feeling a strange mix of pride, excitement, and disbelief that we’re already here.
I’m also feeling pretty good about one other thing: that 529 account we’ve been diligently funding for years is now ready and willing to be depleted. 🙂
Back at Hill, we’re saying goodbye to two other young people: our summer interns.
For 16 years, we’ve had an internship program at Hill, and it has been one of those things that has worked well for everyone involved. We get to teach smart young people about our business, evidence-based investing, and what we’ve learned along the way. They get real exposure to a working investment firm. And, yes, they also help us with some of the work no one else is exactly fighting to do.
Our process is pretty simple. In the fall, we begin collecting interest. Interviews start in January, and we generally make our decisions by mid-March. Depending on the strength of the pool, we hire anywhere from zero to three interns.
This year, we had two of the best we’ve ever had.
They didn’t just show up and take from our culture. They contributed to it. They asked good questions, did good work and made Hill better while they were here. By the end of the summer, we honestly didn’t want them to leave.
Then they did something that made me even more impressed with them: they introduced us to several friends they thought might be great Hill interns next summer. Think about that. They were helping us, helping their friends and putting their own reputations behind the experience they had here.
So I took a few of these prospective interns to lunch.
One of them, a student-athlete at Washington University, asked me a terrific question:
“I know people who manage big money, pick stocks (rather than take an evidence-based approach), and do quite well. What do you say to that?”
I loved the question because it gets at one of the foundational reasons Hill Investment Group exists.
There were five of us sitting at the table, so I said:
“Imagine the five of us take a trip to Vegas. You have a choice. You can be a player or the house. Which would you choose?”
Without hesitating, he said, “I’d be the house.”
“Why?” I asked.
“Because the math is figured out. The odds are on your side.”
Exactly.
We want to be the house.
A player can win tonight. He might win tomorrow night. He might even have an incredible weekend and come home convinced he has figured out Vegas.
But over enough time and enough bets, the house has the advantage.
Investing is different from gambling, of course, but the lesson about odds is remarkably similar. We don’t believe our job is to guess which stock will outperform next year or find the person who had the hottest hand last year. There will always be people who win that game for a while.
We would rather put the odds on our side over the long haul (or Hall).
That means letting markets work for us. Diversifying. Keeping costs and taxes in mind. Staying disciplined when other people aren’t. And accepting that a sound process can sometimes lose to a lucky outcome in the short run.
It’s less exciting than believing someone has discovered the next great stock.
It’s also much more durable.
That’s what we believe to our core at Hill. It’s what we teach our interns. It’s how we invest our own money. It’s how we build our ETFs. And it’s the philosophy we hope these two young people carry with them long after they’ve forgotten whatever projects we made them work on this summer.
Whether you’re heading off to college, beginning a career or investing for the next several decades, you can’t control how everything turns out.
But you can do an awful lot to put the odds on your side.
Take the Long View,