
Signal vs. Noise: Stock Market Concentration Concerns
The Player or the House?
We’re in the Hospitality Business
Client-Exclusive Webinar with David Booth, Co-Founder and Chairman of Dimensional
A Good Estate Plan Should Make Life Easier
Category: Planning
Your Medicare Coverage Deserves a Second Look
 Medicare often arrives as a stack of notices, coverage summaries, and marketing, while the decisions underneath are deeply personal.
Your health changes. Your doctors change. Prescription needs evolve. And Medicare plans can change their premiums, benefits, provider networks, and covered medications. A plan that worked beautifully three years ago might not be the right choice now.
That’s why we encourage clients to take a fresh look at their Medicare coverage, particularly when something meaningful has changed.
The lowest premium isn’t always the lowest cost. And the most expensive plan isn’t necessarily the best. What matters is finding coverage that fits your health needs, preferred doctors, prescriptions, travel habits, and comfort with out-of-pocket expenses.
Medicare’s annual Open Enrollment period runs from October 15 through December 7, providing an opportunity to review and make changes to Medicare Advantage and Part D prescription drug coverage for the coming year. Medicare Supplement policies have different rules and enrollment considerations, making it especially important to understand your options before making a change.
At Hill Investment Group, we believe good financial planning is about much more than managing investments. It’s about helping you make thoughtful decisions that improve your life and give you greater peace of mind. Healthcare coverage is certainly part of that equation.
We don’t pretend to be Medicare experts. But we know people who are. Our role is to help you recognize when a review makes sense and connect you with knowledgeable professionals who can evaluate your options.
If you haven’t reviewed your Medicare coverage recently, or your circumstances have changed, we’d encourage you to reach out. We’ll help get the right conversation started.
Taking the long view means paying attention to more than your portfolio. Sometimes, it’s the decisions outside your portfolio that deserve the most attention.
The 10-Year Treasury Hit 5%. Now What?

The yield on the 10-year U.S. Treasury recently crossed 5%, a level that has attracted plenty of attention in the financial media. That makes sense. Five percent is a memorable number.
From an investment perspective, though, there is nothing magical about 5%.
Interest rates matter. Changes in rates affect borrowing costs, bond yields, business decisions, and the broader economy. But a Treasury yield crossing an arbitrary round number does not suddenly make the information more useful for making investment decisions.
The better question is whether anything about the current interest-rate environment should cause us to change the way we invest.
We don’t believe it should.
Bond markets are forward-looking. Before the Federal Reserve’s most recent rate increase, Treasury yields had already moved higher as investors increasingly expected the Fed to act. When the Fed finally announced the increase, relatively little happened to yields because the market had already anticipated the news.
More importantly, every dollar in a portfolio has a job. Stocks are primarily responsible for long-term growth, while bonds tend to preserve capital and insulate portfolios from large stock market swings.
Higher rates don’t change that job. In fact, higher yields generally improve the return potential of bonds going forward. Earning a little more from the part of the portfolio designed for stability isn’t a bad outcome.
Higher interest rates are frequently presented as bad news for stocks because they increase financing costs. But the relationship isn’t nearly that simple. The Federal Reserve often raises rates when economic conditions are strong and cuts them when economic conditions weaken. These competing narratives – higher financing costs versus a strong economy – make it difficult to predict if rising rates might be good or bad for stocks. Market participants make this evaluation every day and reflect those expectations in stock prices.
Rather than trying to decide which story sounds better, let’s study the data.
We looked at the historical record of US stock market returns and interest rate changes from 1979 through 2025, then we separated calendar years based on whether the 10-year Treasury yield rose or fell during the year.
The results are remarkably similar.
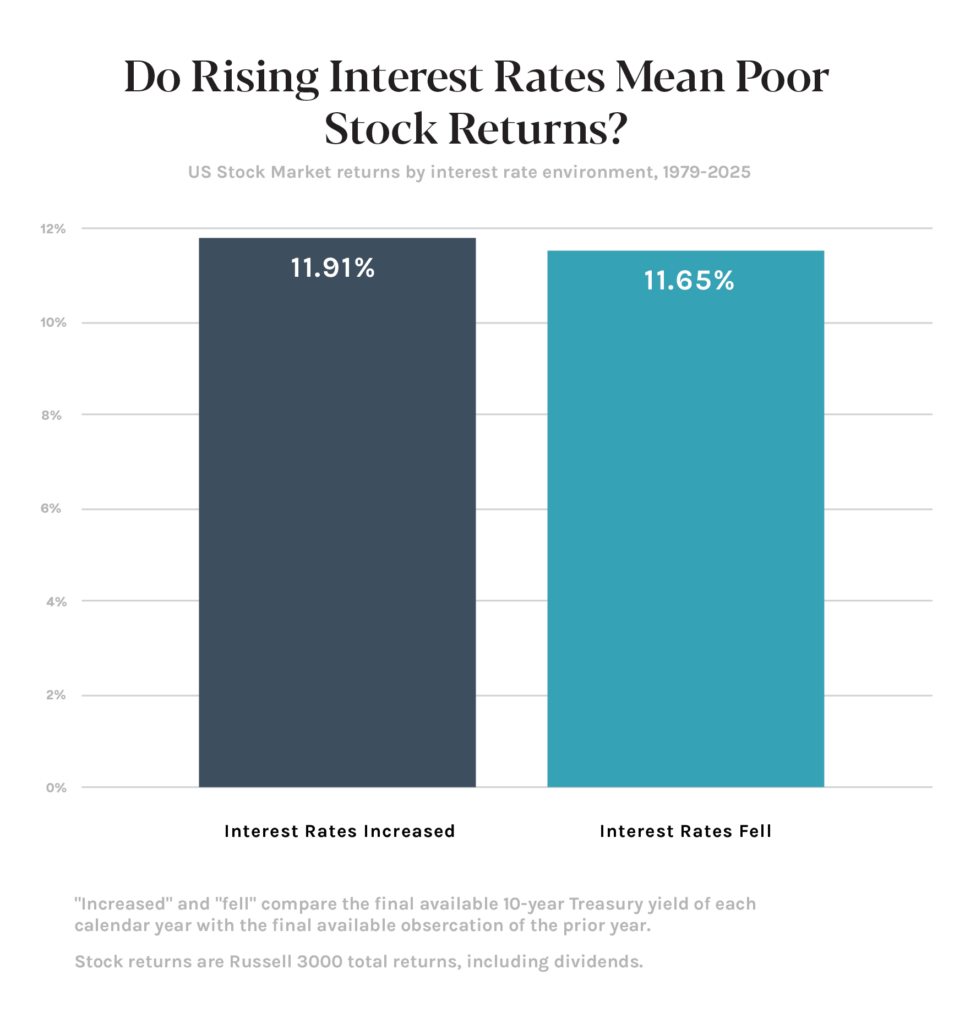
In years where rates increased, US stocks delivered an average return of 11.9%. In years where rates decreased, the average return was 11.6%. A difference of just 0.3%.
The takeaway is not that rising rates are good or bad for stocks. It is that markets incorporate expectations about changing interest rates into stock prices. Investors don’t need to predict the direction of rates to capture the long-term returns stocks are expected to provide.
Rising rates do not spell doom for stocks, nor do they provide a reason to change a well-designed financial plan. Historically, the direction of interest rates has told us very little about future stock market returns.
For investors, there is no special significance to the 10-year Treasury yielding 5% instead of 4.9%. It is a round number that makes for an interesting headline, but it doesn’t change the role of stocks or bonds in a well-designed portfolio.
Bonds still have the same job in our portfolios: preserving capital and dampening stock market swings. Higher yields simply allow them to earn more while doing it.
Our stock investments remain the portfolio’s primary source of long-term growth. Nearly five decades of market history give us little reason to treat rising interest rates as a useful signal about future stock returns.
Financial headlines will change. Round numbers will come and go. The principles behind a well-designed investment plan don’t change with them.
The Freedom to Choose What Comes Next
We recently sat down with a couple in their 50s who had spent decades building. Careers. A portfolio. A family. They funded education, paid down debt, and prepared for a future that always seemed to require one more year of work and one more dollar saved.
For most of that time, every dollar had a job. Pay down the mortgage. Fund college. Max out retirement plans. Set aside cash for taxes. Invest the next business distribution.
Now their cash flow is beginning to look different. Many of the major assignments are covered, which means more of the next dollar comes with a choice.
They like their work and still have goals. They also care deeply about having time for the relationships that matter to them, especially family, friends, and their own parents.
That led us to a more interesting question:
The next dollar could go into the portfolio. It could pay for help that creates breathing room, fund a longer family visit, support a cause, help the kids, or simply wait until the right use becomes clearer.
The right answer depends on the person.
Every client has some mix of assigned dollars and choice dollars, and that mix changes over time. For someone still building, preferences help determine which goals deserve priority. For someone with more room in the plan, those same preferences can help direct that freedom.
Our founder, Rick Hill, offers one example. Rick spent a good solid decade following what we called the “Rick Hill Plan,” slowly walking down from working 40 hours a week to 10. He still keeps his toe in the water, giving him the community, mental engagement, and fun he gets from work while creating more time for family, friends, travel, and hobbies.
That plan fits Rick. Someone else may love working full time. Another person may want to leave work completely and move toward something new. Research on gradual retirement has found benefits to maintaining meaningful work and connection when the arrangement fits the person.
A financial plan tells us what is possible. Knowing the client helps us understand what those possibilities are for.
One family may buy a second home because it becomes the place where everyone gathers. Another may prefer the freedom to travel anywhere. One client may help the kids earlier because they want to see what the money makes possible. Another may value the confidence their children develop by building independently.
Research supports the importance of this fit. One study examining more than 76,000 bank transactions found that people whose spending better matched their personalities reported greater life satisfaction. The fit between the spending and the person mattered more than how much they spent.
The useful question is whether your spending looks like you.
Money can remain invested. Time with parents, children, friends, and our own health has a season. The way we use our resources influences who receives our attention, what receives our energy, and what we have room to experience now.
Understanding our preferences takes its own kind of work and awareness. Clients rarely arrive with perfectly articulated answers, so we help draw them out.
We may notice that a client lights up when talking about traveling with her siblings and grows quiet when discussing a second home. We may learn that “working less” is really about seeing aging parents more often. We may ask whether helping a child is meant to create opportunity, security, or connection.
We ask questions, listen for patterns, and reflect preferences back. Then we put numbers around the choices so clients can decide with confidence.
- Which trips leave you restored and excited?
- What do you hope helping the kids will make possible?
- Who and what do you want more time for?
The couple we met with is still in the gray. They are becoming more aware of their choices and more intentional about what they want their dollars to do.
Good financial planning helps turn wealth into a life well lived. For clients who are building, that means protecting what matters along the way. For clients with more freedom, it means giving more of their lives to what matters most.
For years, your money had a job. Now you may have more freedom to choose its next assignment.
