
Signal vs. Noise: Stock Market Concentration Concerns
The Player or the House?
We’re in the Hospitality Business
Client-Exclusive Webinar with David Booth, Co-Founder and Chairman of Dimensional
A Good Estate Plan Should Make Life Easier
A Good Estate Plan Should Make Life Easier
 We believe estate plans should be as simple and straightforward as they can be.
That doesn’t mean there’s never a place for complexity. Sometimes there absolutely is. But every additional trust, restriction, or strategy should have a clear purpose. Families change. Assets change. Laws change. Priorities change. A good estate plan needs enough flexibility to change with them.
When we talk with clients about their estate plans, one of the first things we look at is the attorney drafting the plan.
Do they specialize in estate planning in your state? Do they serve other clients like you? Are they responsive? Do you trust them? Are their fees reasonable for the work they’re doing? And maybe most importantly: Is this someone you’d feel comfortable having your children work with someday?
We’ve intentionally chosen not to have an estate attorney on staff at Hill. Estate planning attorneys have different specialties and strengths, and the more complex a client’s situation becomes, the more important it is to have the right attorney for that particular work. We’d rather help our clients find the right fit and then work closely with that person.
As for the estate plan itself, reviewing your plan every five years is a good rhythm. Of course, life and tax laws don’t always follow a five-year schedule. A marriage, divorce, death in the family, move to another state, business transaction, or significant change in wealth could all be reasons to revisit things sooner.
Part of our job is helping clients recognize when it’s time to take another look. And if we haven’t reviewed your estate plan recently, that doesn’t necessarily mean something is wrong or has been overlooked. You may just not have hit one of those checkpoints yet.
We also want to make sure your estate plan and investment plan are actually working together. That means checking things like beneficiary designations and account titling, thinking through where cash will come from for taxes or family needs, and making sure any charitable giving is structured in a way that gives your family the flexibility you intended.
None of these topics is particularly flashy, but they’re often the details that determine whether an estate plan works the way you hope it should.
Our role isn’t to design the most sophisticated estate plan possible. It’s to ask excellent questions, identify things that may not line up, and work alongside your attorney to get them resolved.
At the end of the day, the goal is pretty simple: a plan that reflects what you want, can adapt as life changes, and isn’t unnecessarily complex for the people you’re ultimately creating it for.
Have a question about your own estate plan? Click here to schedule time to talk with us.
More Babies, More Perspective
One of the great things about being a financial planner is that we work with clients in all stages of life. We get the benefit of their collective wisdom on money, careers, marriage, parenting, and just about everything in between.
Before maternity leave for our second baby, one common refrain from clients with more than one child was, “Two kids are harder than one.” Three months in, I can safely confirm this is true!
But I’ve also been surprised by how much easier some things feel the second time around. Things that felt so hard with my first are now just part of the routine. And the new things that initially felt impossible with two? You do them a few times, and those become normal, too.
The biggest difference is perspective.
I still worry. I still obsess over which baby product will solve the problem of the day. And I still have plenty of moments when I have no idea what I’m doing. But this time around, I’m better at recognizing what deserves my attention—and what probably doesn’t. Experience has a way of doing that.
The same is true with investing. Markets give us an endless supply of data, headlines, predictions, and reasons to wonder whether this time is different. Taking the Long View doesn’t mean ignoring what’s happening around us. It means having the perspective to recognize what matters and the discipline not to react to what doesn’t.
Maternity leave has given me another kind of perspective, too. Like all of us at Hill, my family is also a client of the firm. Over the past few months, I haven’t had much time to think about markets or financial headlines. And honestly, that’s been just fine. We know where our plan is going. We trust our team and the process. Our financial life doesn’t require our constant attention, which has allowed us to give our attention to something that deserves all of it.
Having a second child has also prompted bigger conversations with my husband: How have our values as a family changed? What do we want our kids to learn about money? What do we want to prioritize as a family? What do we want our money to make possible, now and decades from now?
Those questions matter far more to us than what the market did this week.
Having a second child hasn’t made life less complicated. If anything, it’s made it more so. But it has given me a little more perspective about what deserves my attention—and what doesn’t. And I’m learning that’s a pretty valuable perspective to have in parenting, investing, and just about everything in between.
The 10-Year Treasury Hit 5%. Now What?

The yield on the 10-year U.S. Treasury recently crossed 5%, a level that has attracted plenty of attention in the financial media. That makes sense. Five percent is a memorable number.
From an investment perspective, though, there is nothing magical about 5%.
Interest rates matter. Changes in rates affect borrowing costs, bond yields, business decisions, and the broader economy. But a Treasury yield crossing an arbitrary round number does not suddenly make the information more useful for making investment decisions.
The better question is whether anything about the current interest-rate environment should cause us to change the way we invest.
We don’t believe it should.
Bond markets are forward-looking. Before the Federal Reserve’s most recent rate increase, Treasury yields had already moved higher as investors increasingly expected the Fed to act. When the Fed finally announced the increase, relatively little happened to yields because the market had already anticipated the news.
More importantly, every dollar in a portfolio has a job. Stocks are primarily responsible for long-term growth, while bonds tend to preserve capital and insulate portfolios from large stock market swings.
Higher rates don’t change that job. In fact, higher yields generally improve the return potential of bonds going forward. Earning a little more from the part of the portfolio designed for stability isn’t a bad outcome.
Higher interest rates are frequently presented as bad news for stocks because they increase financing costs. But the relationship isn’t nearly that simple. The Federal Reserve often raises rates when economic conditions are strong and cuts them when economic conditions weaken. These competing narratives – higher financing costs versus a strong economy – make it difficult to predict if rising rates might be good or bad for stocks. Market participants make this evaluation every day and reflect those expectations in stock prices.
Rather than trying to decide which story sounds better, let’s study the data.
We looked at the historical record of US stock market returns and interest rate changes from 1979 through 2025, then we separated calendar years based on whether the 10-year Treasury yield rose or fell during the year.
The results are remarkably similar.
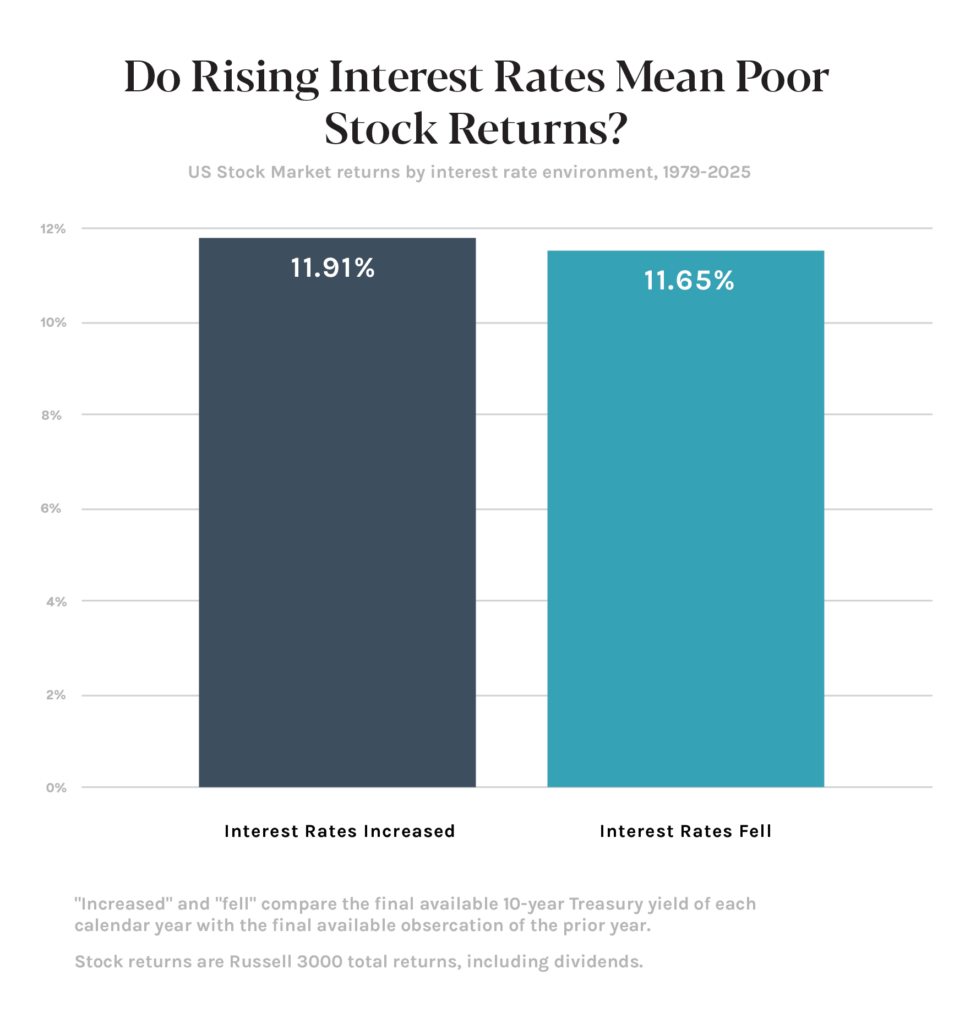
In years where rates increased, US stocks delivered an average return of 11.9%. In years where rates decreased, the average return was 11.6%. A difference of just 0.3%.
The takeaway is not that rising rates are good or bad for stocks. It is that markets incorporate expectations about changing interest rates into stock prices. Investors don’t need to predict the direction of rates to capture the long-term returns stocks are expected to provide.
Rising rates do not spell doom for stocks, nor do they provide a reason to change a well-designed financial plan. Historically, the direction of interest rates has told us very little about future stock market returns.
For investors, there is no special significance to the 10-year Treasury yielding 5% instead of 4.9%. It is a round number that makes for an interesting headline, but it doesn’t change the role of stocks or bonds in a well-designed portfolio.
Bonds still have the same job in our portfolios: preserving capital and dampening stock market swings. Higher yields simply allow them to earn more while doing it.
Our stock investments remain the portfolio’s primary source of long-term growth. Nearly five decades of market history give us little reason to treat rising interest rates as a useful signal about future stock returns.
Financial headlines will change. Round numbers will come and go. The principles behind a well-designed investment plan don’t change with them.
