
Signal vs. Noise: Stock Market Concentration Concerns
A New Book, A Familiar Message: Stay Calm
The Freedom to Choose What Comes Next
Living Our Values: Reflections From Hill’s 2026 Summer Interns
The Player or the House?
Tag: Hill Investment Group
Living Our Values: Reflections from Hill’s 2025 Summer Interns
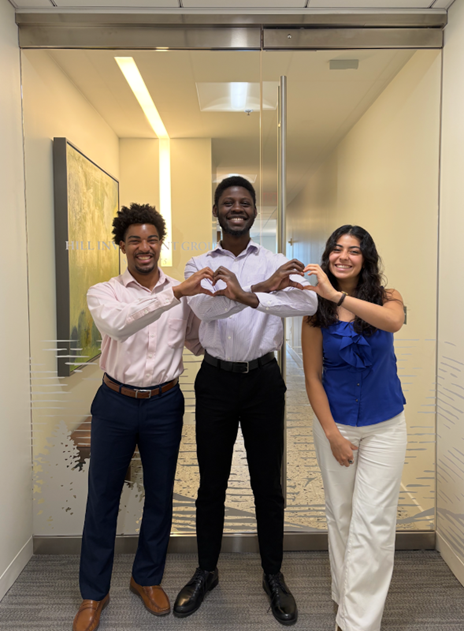
At Hill, we strive to make our backstage values visible on the front stage. In other words, how we work is just as important as what we achieve. We aim to live our values daily so clearly that even our newest team members can recognize them in action, and our clients can see them, too.
As our 2025 summer interns wrap up their time with us, we asked each of them to reflect on their experience and share how they observed Hill’s culture at work.
Last month’s summer party was a great example of how Hill blends business with fun. Remote team members flew in, and I finally got to meet people I’d only seen on Zoom. Connecting in a relaxed, in-person setting made the team feel even more welcoming and real.
The event also marked Hill’s 20-year anniversary—an experience I feel lucky to have shared. Hearing stories from long-time team members gave me perspective on the firm’s journey and the values that built it. What stood out most was how intentionally Hill celebrates people and milestones. It’s clear that fun and community are a meaningful part of how the team stays connected and motivated.
My time at Hill deepened my understanding of evidence-based investing in ways I didn’t expect. From the beginning, I was given meaningful work and encouraged to understand the “why” behind it. I was introduced early on to the Fama-French Five-Factor Model, which helped me connect ideas like profitability and market cap to Hill’s investment philosophy.
That first project sparked curiosity, and I kept exploring. Team members offered resources, asked great questions, and created space for learning. Their support made it clear that growth is a shared value here.
A standout moment for me was building a model for trades. It was more complex than I anticipated, and I went through several rounds of refinement. It would have been easy to rush, but I reminded myself that precision matters more than speed.
With help from the team, I asked questions, improved steadily, and ultimately built something I was proud of—not just for the outcome, but for how I got there. I saw firsthand how patience and discipline are part of Hill’s daily rhythm.
Hey, Hill: Should I Consider a Roth Conversion?
At Hill Investment Group, we’ve found that when a few clients ask similar questions, many more are likely thinking the same thing. To better serve you, we’re introducing our “Hey Hill” newsletter series—addressing common client questions and sharing our perspective.
To submit a question for a future post, email us at service@hillinvestmentgroup.com
Is a Roth IRA Conversion Right for You?
Roth IRA conversions can be a valuable, but often misunderstood tool in long-term financial planning. When thoughtfully timed and executed, they may provide tax advantages, increased flexibility, and legacy planning benefits. But like most financial strategies, they’re not one-size-fits-all.
So how do you know if a Roth conversion might make sense for your situation?
What Is a Roth Conversion?
A Roth IRA conversion means moving money from a pre-tax retirement account—such as a Traditional IRA—into a Roth IRA. You’ll pay ordinary income taxes on the converted amount in the year of the transfer. From that point forward:
- Your investments may grow tax-free inside the Roth
- You can make tax-free withdrawals in retirement (if IRS rules are followed)
In essence, you’re trading a tax bill today for the potential of tax-free growth and withdrawals in the future.
Who Might Want to Consider a Conversion?
A Roth conversion may be worth exploring if:
- You expect to be in a higher tax bracket later
- You can pay the tax bill from non-retirement assets, leaving your retirement funds intact
- You’re in a temporarily low-income year (e.g., early retirement, career break, or sabbatical)
- You’re planning for heirs—Roth IRAs aren’t subject to required minimum distributions (RMDs), which may make them attractive in legacy planning
- You don’t need the money soon—the longer Roth funds grow tax-free, the more powerful the benefit
How It Can Support Your Long-Term Plan
When aligned with your overall strategy, a Roth conversion can:
- Reduce future RMDs and lower taxable income in retirement
- Diversify your tax “buckets,” giving you flexibility in how you draw income
- Potentially ease your heirs’ future tax burden by leaving them tax-advantaged assets
- Help you build more predictable after-tax income over time
It’s a classic example of playing the long game—something we believe in deeply at Hill.
When It Might Not Make Sense
A Roth conversion isn’t ideal for everyone. It may not be the right move if:
- You’d need to use retirement funds to pay the conversion tax
- You’re already in a high tax bracket and expect it to be lower in the future
- You’ll need access to the converted funds within five years (each conversion starts a separate 5-year clock for penalty-free withdrawals)
The Bottom Line
Roth conversions can be powerful, but the decision is nuanced. The tax rules are complex. The upfront cost can be significant. And timing matters.
That’s where we come in. Through our advisory relationships, we help clients model the long-term impact of a Roth conversion—year by year—so they can move forward with clarity and confidence.
At Hill, we don’t just focus on what’s smart today. We help you make decisions that align with your long-term goals and legacy.
Thinking about a Roth conversion? Let’s explore whether it’s a fit—for your plan, your family, and your future.
Disclosures:
Hill Investment Group is an SEC-registered investment adviser. Registration does not imply a certain level of skill or training. The information provided is for educational purposes only and should not be construed as personalized investment, tax, or legal advice. Roth IRA conversions involve complex tax considerations and may not be appropriate for all investors. Consult your tax advisor or financial professional before implementing any financial strategy. Investing involves risk, including the possible loss of principal. Past performance is not indicative of future results.
Signal vs. Noise: Cutting Through the Clutter of Financial Advice Online
It’s never been easier or more overwhelming to get financial advice. Open your phone and you’ll likely see someone with a large following and bold opinions telling you what to do next with your money. Scroll your feed and it’s hard to miss: dramatic predictions, attention-grabbing “can’t-miss” trades, and influencers claiming to decode the secrets of building wealth.
Welcome to the age of the “finfluencer.” While some have genuine experience, many are focused on views, and not your best interest.
At Hill Investment Group, we believe that real advice should be simple, clear, and grounded in evidence, not hype. That’s why we’re launching a new series to unpack misleading ideas that circulate online or in print.
Our goal? To inform, not entertain. To offer substance, not speculation.
We won’t chase the latest trend. We’ll challenge it with patience, perspective, and real-world research. That’s because, when it comes to your financial future, having a long-term plan that is built on decades of data and thoughtful execution matters more than a viral headline.
We hope this series gives you and those you care about a steady hand in a noisy world. We’ll start next month with one of the most common (and flawed) ideas making the rounds today.
Heard something at work, at golf, or on social media that has you asking, “Should I be paying attention to this?”
Feel free to share it with us. We’d love to help unpack it. Submissions will remain confidential unless we get your permission to share anonymously. Send to: zenz@hillinvestmentgroup.com
Please note: Submissions are reviewed for educational purposes only and do not constitute personalized investment advice.
