
Signal vs. Noise: Stock Market Concentration Concerns
The Player or the House?
We’re in the Hospitality Business
Client-Exclusive Webinar with David Booth, Co-Founder and Chairman of Dimensional
A Good Estate Plan Should Make Life Easier
Meet Annie Hall
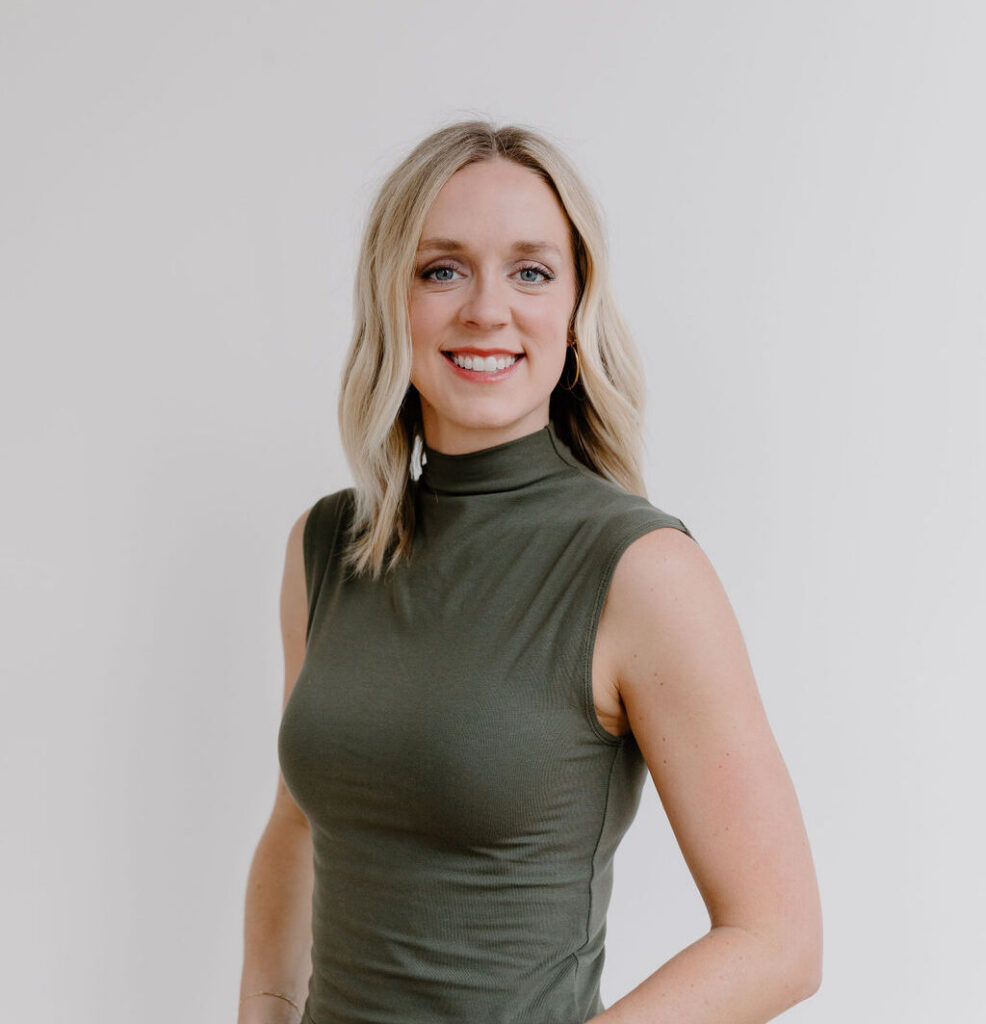
We’re excited to welcome Annie Hall as Marketing Manager at Hill Investment Group and Longview Research Partners after a year of working with our team. Annie’s role spans marketing, growth, and business development across both organizations, including content and editorial planning, client communications, digital marketing, events, and business development coordination.
Annie brings more than a decade of experience across sales, design, technology, and entrepreneurship. During 12 years in Chicago, she spent a decade at luxury design company HOLLY HUNT before moving into technology sales at climate tech company Worldly. She later launched her own business, working independently with leaders and growing companies. That range of experience shapes how she approaches communication, relationships, and bringing ideas to life.
For Annie, joining Hill full time is also a return to familiar ground. I’ve known her since she interned with us in 2009, before graduating from the University of Missouri with a degree in Biology and a minor in Architectural Studies. As co-founder Matt Hall’s younger sister, she also had a front-row seat to Hill’s early days.
Now back in St. Louis, Annie lives with her partner, Nate, and their two rescue dogs. A lifelong tennis player and outdoor enthusiast, she is passionate about animal rescue and is currently training for her first marathon this year in Chicago! See Annie’s full bio here.
A Good Estate Plan Should Make Life Easier
 We believe estate plans should be as simple and straightforward as they can be.
That doesn’t mean there’s never a place for complexity. Sometimes there absolutely is. But every additional trust, restriction, or strategy should have a clear purpose. Families change. Assets change. Laws change. Priorities change. A good estate plan needs enough flexibility to change with them.
When we talk with clients about their estate plans, one of the first things we look at is the attorney drafting the plan.
Do they specialize in estate planning in your state? Do they serve other clients like you? Are they responsive? Do you trust them? Are their fees reasonable for the work they’re doing? And maybe most importantly: Is this someone you’d feel comfortable having your children work with someday?
We’ve intentionally chosen not to have an estate attorney on staff at Hill. Estate planning attorneys have different specialties and strengths, and the more complex a client’s situation becomes, the more important it is to have the right attorney for that particular work. We’d rather help our clients find the right fit and then work closely with that person.
As for the estate plan itself, reviewing your plan every five years is a good rhythm. Of course, life and tax laws don’t always follow a five-year schedule. A marriage, divorce, death in the family, move to another state, business transaction, or significant change in wealth could all be reasons to revisit things sooner.
Part of our job is helping clients recognize when it’s time to take another look. And if we haven’t reviewed your estate plan recently, that doesn’t necessarily mean something is wrong or has been overlooked. You may just not have hit one of those checkpoints yet.
We also want to make sure your estate plan and investment plan are actually working together. That means checking things like beneficiary designations and account titling, thinking through where cash will come from for taxes or family needs, and making sure any charitable giving is structured in a way that gives your family the flexibility you intended.
None of these topics is particularly flashy, but they’re often the details that determine whether an estate plan works the way you hope it should.
Our role isn’t to design the most sophisticated estate plan possible. It’s to ask excellent questions, identify things that may not line up, and work alongside your attorney to get them resolved.
At the end of the day, the goal is pretty simple: a plan that reflects what you want, can adapt as life changes, and isn’t unnecessarily complex for the people you’re ultimately creating it for.
Have a question about your own estate plan? Click here to schedule time to talk with us.
More Babies, More Perspective
One of the great things about being a financial planner is that we work with clients in all stages of life. We get the benefit of their collective wisdom on money, careers, marriage, parenting, and just about everything in between.
Before maternity leave for our second baby, one common refrain from clients with more than one child was, “Two kids are harder than one.” Three months in, I can safely confirm this is true!
But I’ve also been surprised by how much easier some things feel the second time around. Things that felt so hard with my first are now just part of the routine. And the new things that initially felt impossible with two? You do them a few times, and those become normal, too.
The biggest difference is perspective.
I still worry. I still obsess over which baby product will solve the problem of the day. And I still have plenty of moments when I have no idea what I’m doing. But this time around, I’m better at recognizing what deserves my attention—and what probably doesn’t. Experience has a way of doing that.
The same is true with investing. Markets give us an endless supply of data, headlines, predictions, and reasons to wonder whether this time is different. Taking the Long View doesn’t mean ignoring what’s happening around us. It means having the perspective to recognize what matters and the discipline not to react to what doesn’t.
Maternity leave has given me another kind of perspective, too. Like all of us at Hill, my family is also a client of the firm. Over the past few months, I haven’t had much time to think about markets or financial headlines. And honestly, that’s been just fine. We know where our plan is going. We trust our team and the process. Our financial life doesn’t require our constant attention, which has allowed us to give our attention to something that deserves all of it.
Having a second child has also prompted bigger conversations with my husband: How have our values as a family changed? What do we want our kids to learn about money? What do we want to prioritize as a family? What do we want our money to make possible, now and decades from now?
Those questions matter far more to us than what the market did this week.
Having a second child hasn’t made life less complicated. If anything, it’s made it more so. But it has given me a little more perspective about what deserves my attention—and what doesn’t. And I’m learning that’s a pretty valuable perspective to have in parenting, investing, and just about everything in between.
