
Signal vs. Noise: Stock Market Concentration Concerns
The Player or the House?
We’re in the Hospitality Business
Client-Exclusive Webinar with David Booth, Co-Founder and Chairman of Dimensional
A Good Estate Plan Should Make Life Easier
The 10-Year Treasury Hit 5%. Now What?

The yield on the 10-year U.S. Treasury recently crossed 5%, a level that has attracted plenty of attention in the financial media. That makes sense. Five percent is a memorable number.
From an investment perspective, though, there is nothing magical about 5%.
Interest rates matter. Changes in rates affect borrowing costs, bond yields, business decisions, and the broader economy. But a Treasury yield crossing an arbitrary round number does not suddenly make the information more useful for making investment decisions.
The better question is whether anything about the current interest-rate environment should cause us to change the way we invest.
We don’t believe it should.
Bond markets are forward-looking. Before the Federal Reserve’s most recent rate increase, Treasury yields had already moved higher as investors increasingly expected the Fed to act. When the Fed finally announced the increase, relatively little happened to yields because the market had already anticipated the news.
More importantly, every dollar in a portfolio has a job. Stocks are primarily responsible for long-term growth, while bonds tend to preserve capital and insulate portfolios from large stock market swings.
Higher rates don’t change that job. In fact, higher yields generally improve the return potential of bonds going forward. Earning a little more from the part of the portfolio designed for stability isn’t a bad outcome.
Higher interest rates are frequently presented as bad news for stocks because they increase financing costs. But the relationship isn’t nearly that simple. The Federal Reserve often raises rates when economic conditions are strong and cuts them when economic conditions weaken. These competing narratives – higher financing costs versus a strong economy – make it difficult to predict if rising rates might be good or bad for stocks. Market participants make this evaluation every day and reflect those expectations in stock prices.
Rather than trying to decide which story sounds better, let’s study the data.
We looked at the historical record of US stock market returns and interest rate changes from 1979 through 2025, then we separated calendar years based on whether the 10-year Treasury yield rose or fell during the year.
The results are remarkably similar.
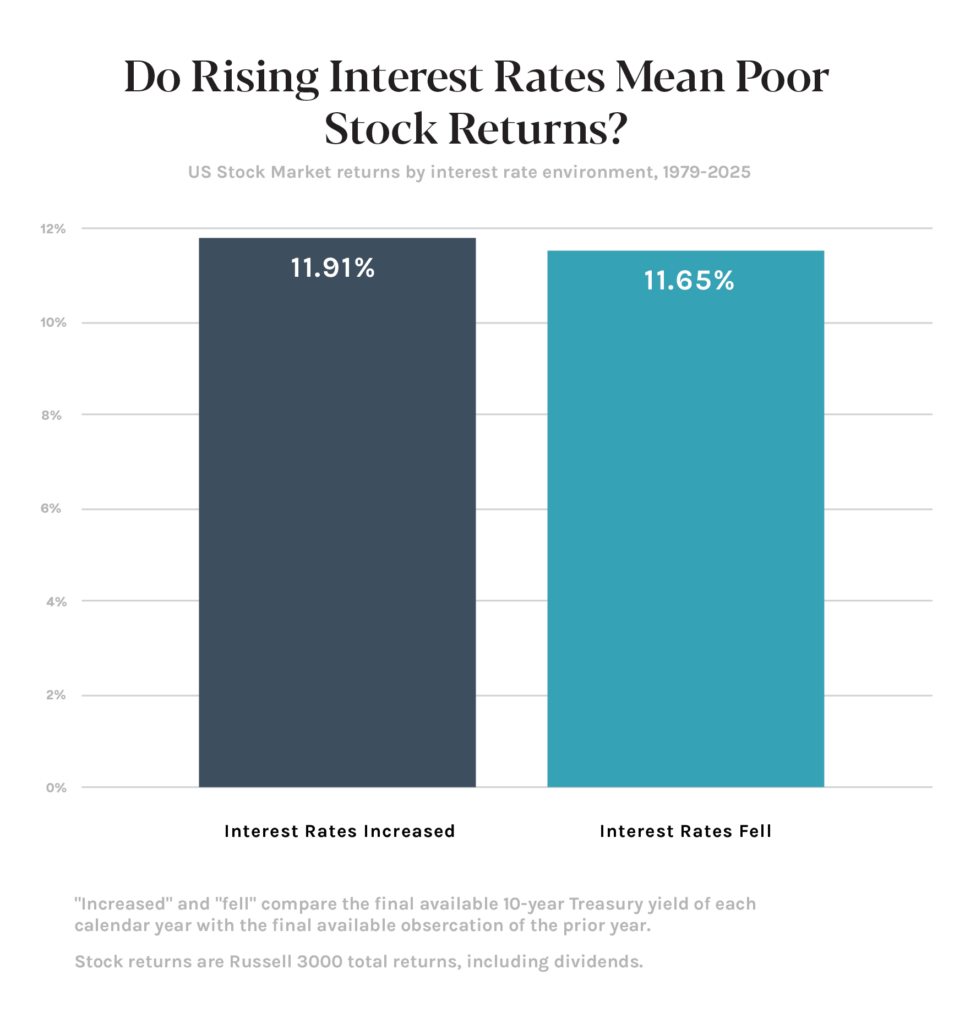
In years where rates increased, US stocks delivered an average return of 11.9%. In years where rates decreased, the average return was 11.6%. A difference of just 0.3%.
The takeaway is not that rising rates are good or bad for stocks. It is that markets incorporate expectations about changing interest rates into stock prices. Investors don’t need to predict the direction of rates to capture the long-term returns stocks are expected to provide.
Rising rates do not spell doom for stocks, nor do they provide a reason to change a well-designed financial plan. Historically, the direction of interest rates has told us very little about future stock market returns.
For investors, there is no special significance to the 10-year Treasury yielding 5% instead of 4.9%. It is a round number that makes for an interesting headline, but it doesn’t change the role of stocks or bonds in a well-designed portfolio.
Bonds still have the same job in our portfolios: preserving capital and dampening stock market swings. Higher yields simply allow them to earn more while doing it.
Our stock investments remain the portfolio’s primary source of long-term growth. Nearly five decades of market history give us little reason to treat rising interest rates as a useful signal about future stock returns.
Financial headlines will change. Round numbers will come and go. The principles behind a well-designed investment plan don’t change with them.
Signal vs. Noise: Stock Market Concentration Concerns
Stop me if you’ve heard this before: The stock market is at record concentration levels. A handful of companies are driving market returns. There’s an AI bubble. FAANG stocks. The Magnificent Seven.
The names change, but the message is familiar. Today, much of the attention is focused on a handful of large technology companies at the center of the AI boom. Their strong performance has made them increasingly influential in the U.S. stock market, and the headlines can make it feel like investors need to do something about it.
The concentration is real. But before reacting to it, an evidence-based investor should step back, put on their Long View lens, and ask a more useful question: What does this actually mean for my portfolio?
The S&P 500 Has Become More Concentrated
Concentration, in investing terms, refers to how much of a portfolio is allocated to a particular stock, sector, country, or other category.
By almost any measure, the S&P 500 is considerably more concentrated today than it was a decade ago:
| Portfolio | Largest Sector Weight | Top Ten Companies Weight |
|---|---|---|
| S&P 500 | Technology – 38% | 38% |
| S&P 500 – 10 years ago | Technology – 20% | 19% |
Data as of June 30, 2026; June 30, 2016 for historical S&P 500.
That matters because concentration makes a portfolio more dependent on a smaller number of outcomes. When a handful of companies represent a large portion of your portfolio, unexpected news that changes the market’s expectations for those companies can have an outsized impact on your results.
But there is an important distinction: the S&P 500 is not your portfolio.
A Global Portfolio Looks Different
Hill Investment Group portfolios aren’t built around the 500 largest companies in a single country. They are built globally, with exposure to more than 14,000 companies across 47 countries.
That changes the picture meaningfully:
| Portfolio | Largest Sector Weight | Top Ten Companies Weight |
|---|---|---|
| S&P 500 | Technology – 38% | 38% |
| HIG Global Portfolio | Technology – 28% | 22% |
Data as of June 30, 2026.
Global diversification naturally reduces the portfolio’s dependence on any single company, sector, or country. The companies driving today’s U.S. market concentration are still there—we own them too—but they represent a smaller portion of the overall portfolio.
Diversification doesn’t mean avoiding the biggest or most successful companies. It means not making your financial future overly dependent on them.
If today’s technology leaders continue to thrive, HIG portfolios participate in that growth. If leadership shifts to different companies, sectors, or countries, we own those too. We don’t need to predict which outcome will occur.
HIG portfolios look much more like the global economy, deviating only when the evidence suggests that doing so can improve expected outcomes for investors.
Built for This Already
Your plan isn’t changing, because it doesn’t need to. Headlines about market concentration can make it feel like investors need to respond to something new. Diversification is one of the oldest ideas in evidence-based investing, and your portfolio has been built for markets like this one since the day we put it together.
Your portfolio includes thousands of companies across developed and emerging markets, large and small, spanning every sector of the global economy. It also leans toward companies with characteristics the evidence associates with higher expected returns: smaller companies, lower relative prices, and stronger profitability.
That structure isn’t designed around today’s headlines. It’s designed for a future we can’t predict.
When one part of the market performs particularly well, the portfolio systematically rebalances rather than allowing yesterday’s winners to dictate tomorrow’s allocation. When market leadership changes, the portfolio already owns the companies positioned to benefit.
That concentration story is real. It’s just about a portfolio built differently than yours.
A New Book, A Familiar Message: Stay Calm
We’re excited about the September 1, 2026, launch of Stay Calm: Learn to Embrace Uncertainty in Investing and Life, by David Booth, Chairman and Co-Founder of Dimensional, our oldest strategic partner. Booth and St. Louis native Rex Sinquefield launched Dimensional in the early 1980’s as the first exclusively evidence-based fund company available to the public.
Clients and longtime followers will recognize the words in title because you’ve likely heard them come out of our mouths or read the words in these pages and client letters. Tune out the noise of today’s headlines. Focus on what you can control. And embrace the uncertainty of the market because that very uncertainty is precisely what will reward you as a long-term investor. Hence, it’s why we say: Take the Long View.
In Stay Calm, David shares the lessons, mindset, and stories behind the revolution that transformed investing from a game of speculation into a discipline grounded in evidence and long-term thinking.
Watch this space for details on an exclusive webinar with David Booth. Until then, read what the likes of Arnold Schwarzenegger, Barry Ritholtz, and Errol Morris are saying about Stay Calm below.
If you’re trying to instill more calm into your life, join our community or give us a call at 314-448-4023.
“Success—in anything, from fitness to business to investing—comes from discipline and patience, not chasing shortcuts. David Booth, who is a visionary and a great friend, reminds us that staying calm, loving the process, and focusing on what we can control is the real path to lasting results. This book is about building strength the smart way—over time.”
—Arnold Schwarzenegger, longtime Dimensional shareholder
“No one has done more to bring the SCIENCE of investing to the broader public than David Booth. His commitment to understanding markets—through deep, evidence-based, academic research—is unparalleled.”
—Barry Ritholtz, Chairman and Chief Investment Officer of Ritholtz Wealth Management
“There was a financial revolution in our time, brought about through a combination of computers, data collection, and theory. David Booth and the University of Chicago were at the center of it. Stay Calm is in part a chronicle of this financial revolution. But more relevantly, it’s a story about scientific principles of investing that shows how easy it is today for anyone to invest well.”
—Errol Morris, Academy Award®–winning filmmaker
